


Real estate Luxembourg: 1 minute of travel time more = −1.2 % on the price
Real estate:
1 minute more
= −1,2 % ?
Statec has for the first time calculated the impact of travel time on prices — and publishes the figures for the 2nde quarter 2026
The Statec and the Habitat Observatory published their quarterly report «Housing in Figures» on Thursday, September 24th. A market that is moving forward in a disorganized manner — and a parallel study that changes the way a property is evaluated in Luxembourg.
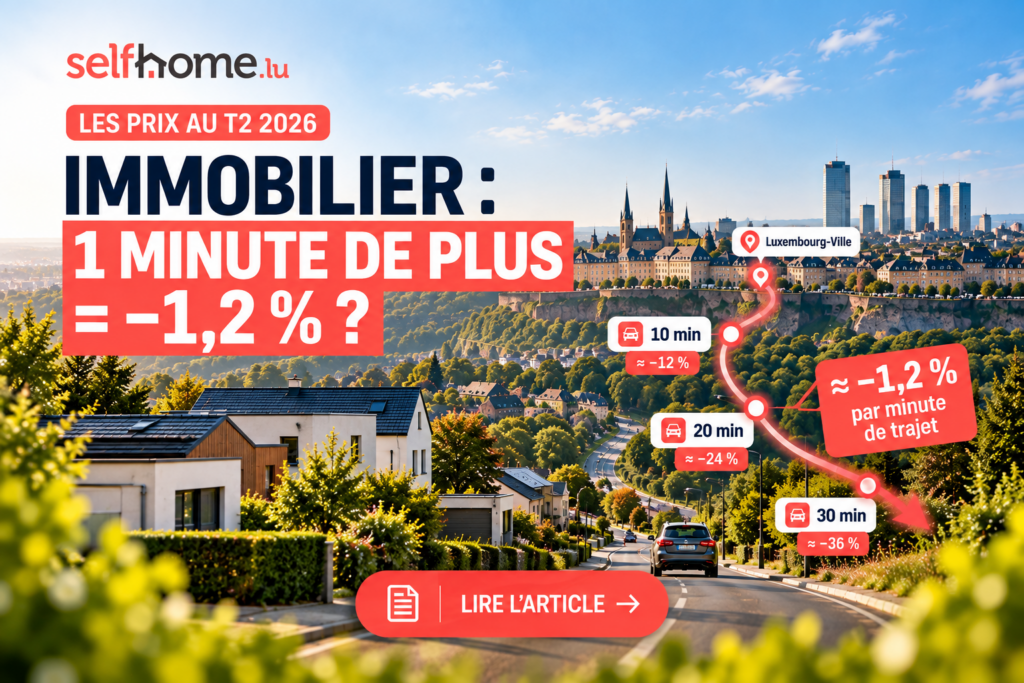
Discovery of the week: −1.2 % per minute of travel time
This is the most concrete information published yesterday. In a parallel study, the Statec quantified the relationship between travel time to the capital and the price of apartments. The model, estimated on 4,015 transactions In 2025, this results in a clear scale of magnitude.
≈ −1,2 %
on the price, per additional minute of travel
towards Luxembourg-Ville
As a matter of fact Illustrative, Applied linearly, this gives a speaking order of magnitude:
⚠️ To be nuanced: this is an average statistical relationship, no automatic discount. The surface area, whether new or old, the basement or parking space also count.
Closeness on the map is not enough
The case of Kockelscheuer is speaking: only 10 km from the center, but 27 minutes' drive due to congestion. Mersch, one and a half times further away, only takes 3 minutes longer.
Since June 2026, Statec has incorporated this criterion into its methodology: travel time now replaces distance in the price index calculation model. No historical index is revised.
A blind spot remains: the study only measures access to Luxembourg City, Without taking into account secondary employment poles such as Esch-sur-Alzette or Nordstad.
The figures from the 2nde quarter 2026
+8.2 % for the quarter
apartments
pre-crisis level
632 million euro in volume
A rebound to be relativized
Over a year, the number of sales decreases by 33,9 %. But beware of the trap: in the spring of 2025, the announced expiration of the tax measures had triggered a rush, with 1,928 sales focused on a single quarter. Comparing this exceptional peak artificially amplifies the impression of a relapse.
The authors rather talk about a « progressive normalization of activity ».
The former has regained its pre-crisis level
This is the healthiest segment of the market: 1,049 existing apartments sold, which is slightly above the 2017-2021 average (about 1,035 sales). Prices are rising +1,3 % for the quarter, but remain −0,6 % below their 2025 spring level.
The nine remain the big injury
Only 225 apartments under construction sold at T2, for approximately €171 million. Despite a rebound of +8.2% % in the quarter, the segment remains down by nearly 68 % at the pre-crisis average (≈ 694 sales).
Important methodological nuance: some new homes already completed They are sold by conventional contract and therefore appear in the statistics of the former. The VEFA do not measure all the new business.
Homes are starting up again, but prices are still falling
709 houses sold (+8.2 % % for the quarter), but the segment remains approximately 1% behind 22 % compared to the average for 2017-2021. And the prices of existing homes are still falling: −0.5 % for the quarter and −3.7 % for the year. The resumption of transactions does not translate into a rise in prices.
Rents accelerate: +5.8 % % year-on-year
over a year
either 2.4× less
For tenants, no respite. The advertised rents for apartments are rising more than twice as fast as inflation.
The explanation advanced by the authors is enlightening: a possible shift towards renting households whose borrowing capacity has been reduced by the rise in interest rates, in the face of a still limited supply of rental properties.
Note: The rents under the lease They only progress by +1.3 % over a year According to the Statec index, the difference is entirely due to new contracts.
What that changes for you
Two good news: house prices continue to fall (−3.7 % over the year) and you now have an objective criterion to arbitrate — the actual travel time, Not the distance. Test your journey during peak hours before you decide. And don’t forget the Bëllegen Akt, which is worth €45,000.
The former has recovered its pre-crisis level in volume: The buyers are here. But prices remain under pressure, especially on homes. A realistic positioning from the outset remains the best strategy.
Announced rents are rising by +5,8 %, With inflation more than double that of the year before, demand is strengthening due to households being excluded from credit. The rental market has never been so lucrative.
The platform that works for you
Individuals and professionals
The market is normalizing; the opportunities are returning. Selfhome.lu has established itself as the benchmark for direct transactions in Luxembourg — zero commission, community of over 30,000 members.
And soon, we are opening our services to Real estate agencies — to offer them a fair alternative to large platforms that crush their margins.
selfhome.lu
#1 in real estate between individuals · Luxembourg
Sources: Statec & Habitat Observatory — «Housing in figures» (24 September 2026) · Statec — study on accessibility and apartment prices (24 September 2026) · Paperjam · Immotop.lu · LISER